Somebody has already been exactly where you are.

Real California transactions. Find the one that sounds like yours and you will see what was actually possible.

Home › Success stories

Will a bridge loan work for my situation?

Almost certainly, yes. No two of these were the same problem. A buyer who kept losing to cash. A founder who needed payroll covered while a funding round landed. A widow who was not going to touch her retirement accounts. A daughter with an inherited house that was not ready to sell.

Which one sounds like you?

“I keep losing to cash offers.” Winning Competitive Deals →“This house no longer fits my life.” Right Sizing and Relocating →“I found the house. I still own mine.” Moving Equity →“My deal is falling apart and we are close to closing.” Saving the Deal →“I inherited a house and I am not sure what to do with it.” Inheritance and Wealth Transfer →“I buy, improve and sell property.” Fix and Flip →“I need capital fast, and it is not for a house.” Hard Money and Founder Loans →

The one Sofia tells first

$500K off the price, and $500K more on the sale

He found us on ChatGPT. He knew exactly what he wanted, filled out the application himself, and then called. Smart, competitive, young family, strong savings. What we liked most was that he saw a bridge loan as a competitive tool. He wanted to win, but only at the right price.

We worked with him for about three months. He walked away from houses that did not feel right. One he had been watching was listed too high and kept dropping; he could tell the listing had lost momentum. He made an offer, two higher ones came in, and he lost it.

Then the winning offer fell through. The opening was his, as long as he could close in fourteen days with no contingencies, no appraisal, and essentially cash. With nobody else at the table he came in well below his first offer. The listing agent was almost offended and was not going to counter. Sofia called her, explained the bridge loan, and made it clear this would close. The seller countered. Without us in the picture there would have been no counter at all.

They went back and forth for nearly a week. Because a bridge loan has no payments until it funds, he stayed in his own home on his own timeline with nobody breathing down his neck. He kept his nerve, his agent kept hers, and they settled on a number the seller was happy with. He got the house for about $500,000 less than he was willing to pay.

Then the other side. They sold the Berkeley home for about $2M against an estimate of $1.5M to $1.7M. Another $500,000 or so more than expected. The bridge loan fee was about two percent, roughly $50,000. They came out close to $950,000 ahead, in a bigger house in a better school district.

Negotiating power, no stress, buying on your own timeline, and selling for top dollar. One loan did all four.

“I keep losing to cash offers.”

Winning Competitive Deals

How this works →
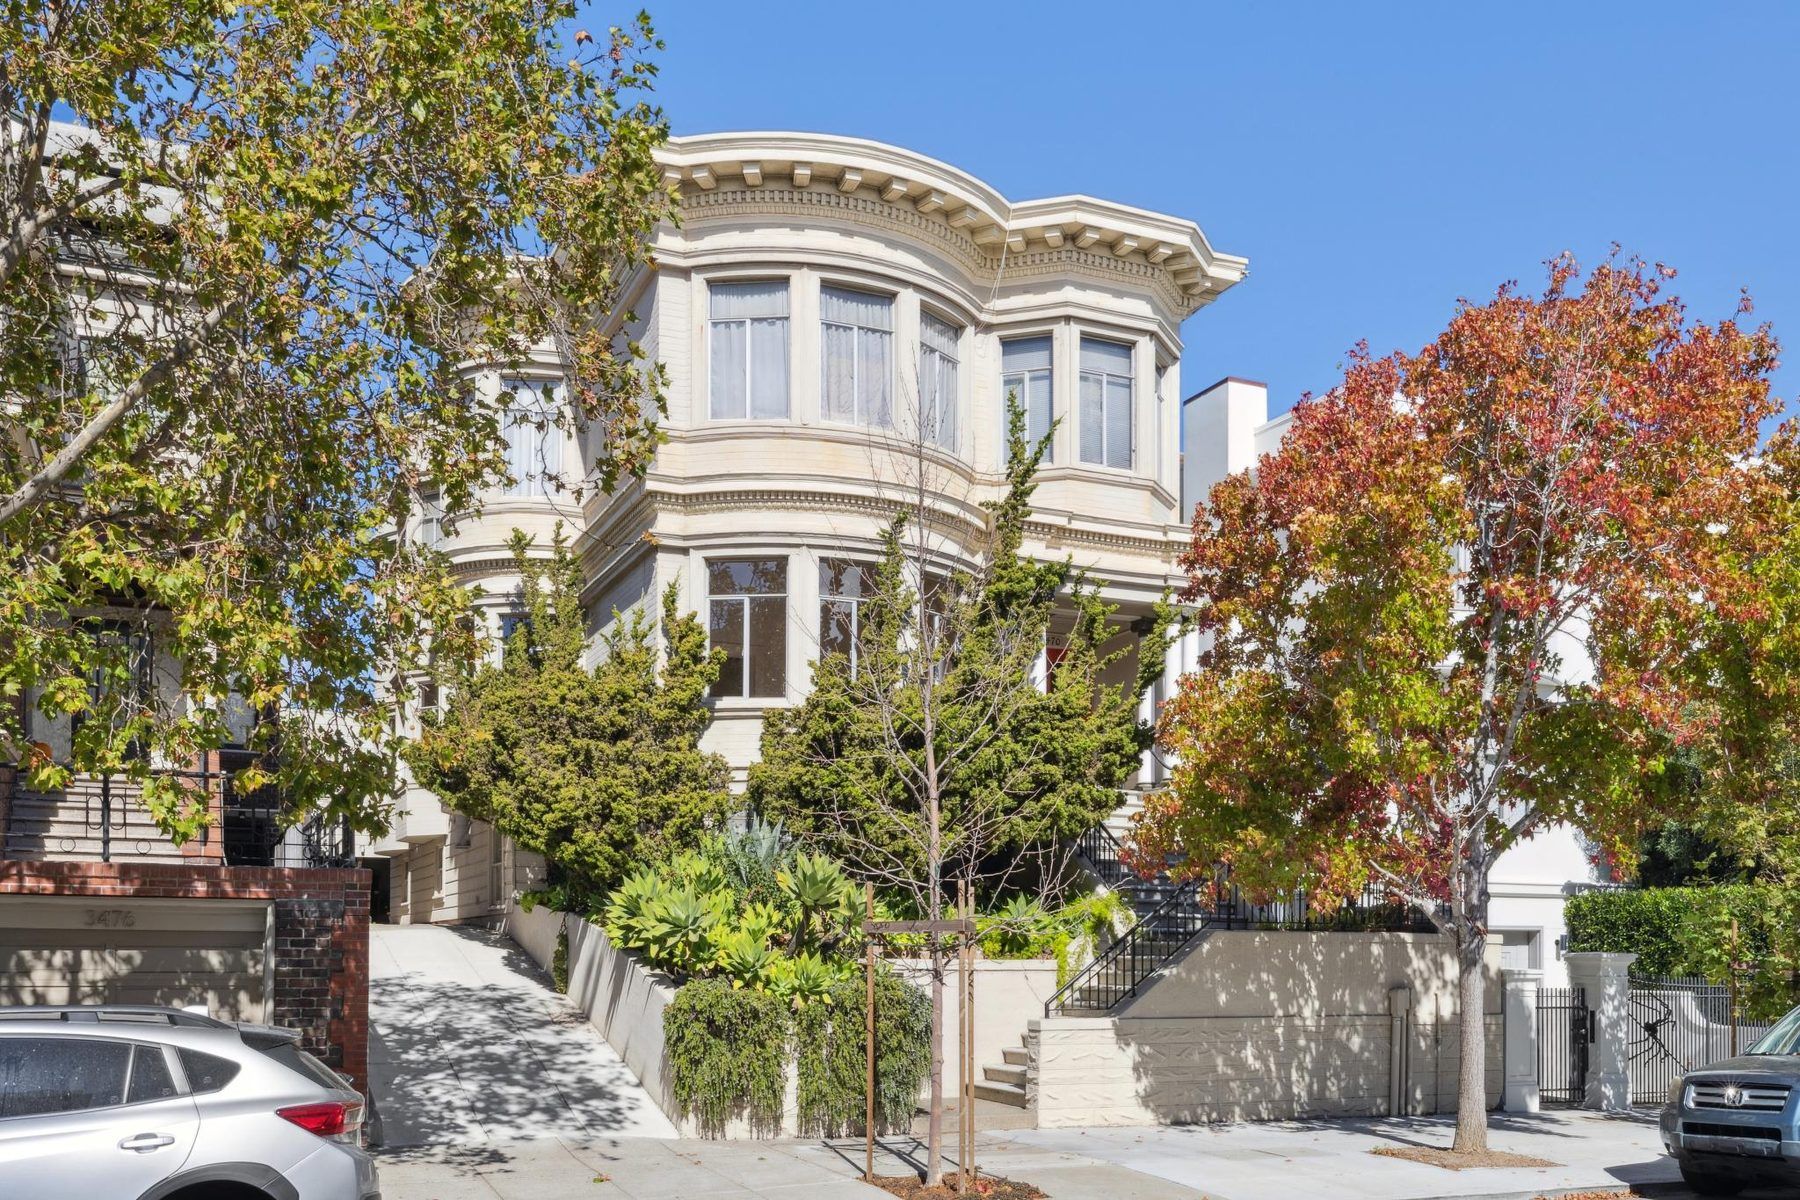
A San Francisco Edwardian with bay windows on a tree-lined street
Photo: Jennifer Rosdail Real Estate Team

The Marina to Mill Valley

A bigger house before the baby arrived

Our clients were in a Marina condo with their first child and she was seven months pregnant with the second. They were not really planning to sell. The plan was to squeeze in, have the baby and work it out later.

Then they went to an open house in Mill Valley at the weekend and fell in love. With San Francisco so hot, this was their chance to sell at the peak. Either this house, or they stayed in the condo.

There were multiple offers, and they were choosing between us and another bridge lender they had not enjoyed working with. We could offer a fourteen-day close with no appraisal. The deciding factor was that we know the Mill Valley listing agent. Sofia called her, and because the offer was as strong as all cash she wanted to make it work. They were not the highest, so she asked them to match the best. They matched it, even though they would have gone higher.

They close in fourteen days with no contingencies and no appraisal, and they will be in before the holidays, before the rain, and before the baby.

Knowing the agent on the other side is not a small thing. It is often the difference.
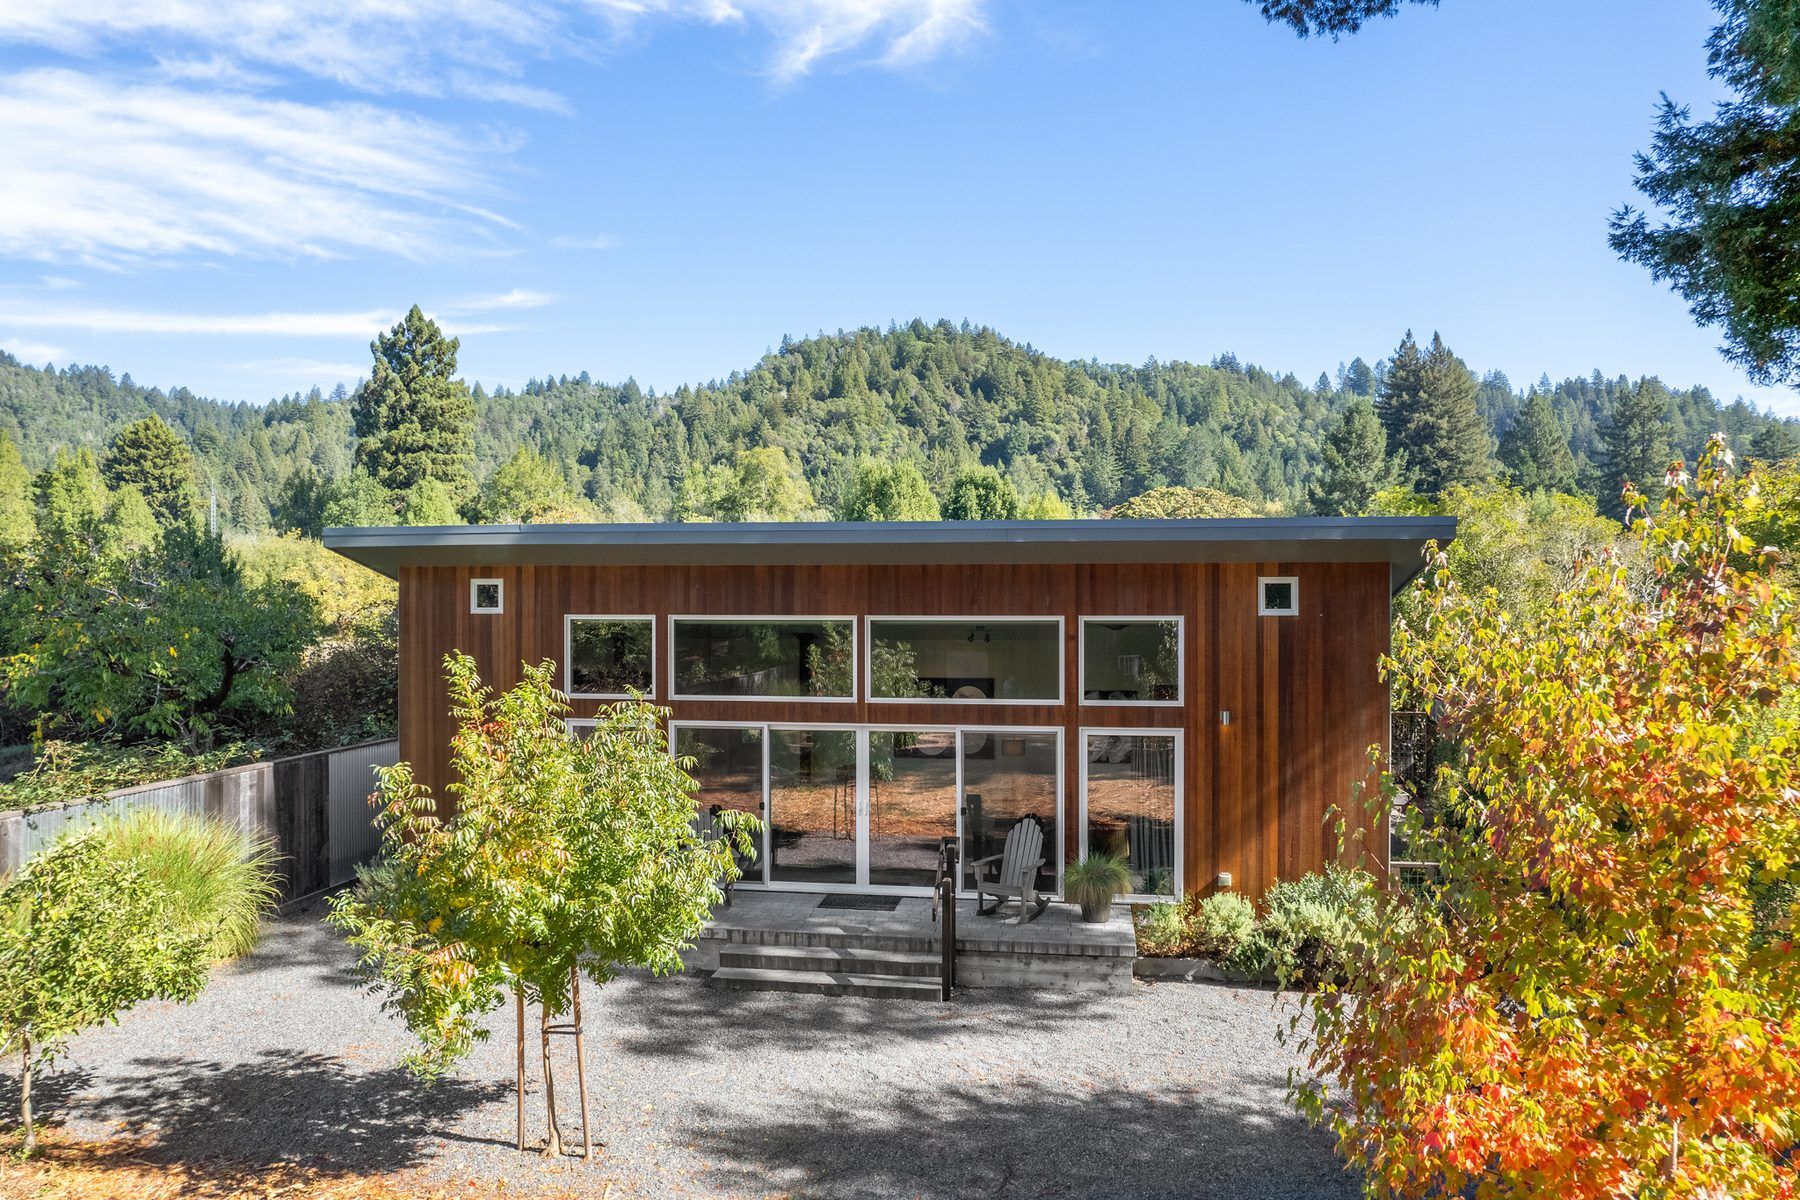
San Rafael

Turning a financed offer into a cash offer

Our clients were upgrading and had their eye on a San Rafael home that drew a crowd of offers. They had $1.4M ready for the deposit and a loan lined up elsewhere. But they were against all-cash offers, and a financed offer was never going to win. Their long-term aim was to carry no mortgage at all.

Their agent had heard the same thing from everyone: call Sofia. He was hesitant and not sure why his clients would need a bridge loan. Once he called, they needed it immediately. The price was $3.1M, so we filled the cash gap with a $1.7M bridge loan without even crossing their other property. They made a cash offer, closed in ten days, and won the house.

Being fully underwritten is not enough against cash. A bridge loan makes a strong buyer a cash buyer.

“In around 48 hours, Sofia performed an absolute miracle. And she did it all with so much positivity, good cheer, and confidence. She turned our stress into GREAT SUCCESS. We WON! My clients were able to purchase their dream home!”

Jason Lewis  ·  Google review

“This house no longer fits my life.”

Right Sizing and Relocating

How this works →
A mid-century home among the redwoods in Guerneville
Photo: Jennifer Rosdail Real Estate Team

Tiburon to Larkspur

Moving on without touching the retirement accounts

Our client had been in her Tiburon home a long time and kept it beautifully. Owned free and clear. A couple of years after her husband died she realised that while she was content there, it was no longer what she wanted. What she wanted was a fifty-five and over community, simpler: no storeys, no hill, a fresh start.

She found a house in Larkspur at a real step down in price, a conservative move. The seller had remodelled it completely and left all the furniture he had bought less than a year before. All she had to do was pack a closet.

On paper she had plenty, around $7.5M in investments and retirement accounts, but under $100K in cash. Her son worked with us and with her financial advisor, who was firmly against touching those accounts. So we lent her the full purchase price. We funded, and she moved out the next day. Her agent now has an empty house to prepare, stage and sell properly, and she never had to juggle buying and selling at once.

You do not have to drain retirement accounts to move. The equity you already have does it.

San Francisco

Selling an empty house for more than expected

Our clients had just entered retirement and had been thinking about leaving their multi-storey San Francisco family home for a simpler condo. We worked with them for nearly a year. They knew exactly what they wanted.

They bought the house decades ago for $438,000. Because they could move straight into the condo, the house went on the market empty, and their listing agent painted, prepped and staged it properly. They listed it the San Francisco way and let the offers come. It is now expected to go for more than the estimate, and they never had to live through any of it.

Moving out first lets your agent sell an empty house for top dollar, and the difference can more than cover the loan.

Carmel to Tiburon

Changing your mind after you have built

Our clients built a beautiful home in Carmel. When construction finished they realised they did not actually want to live in Carmel. They wanted Tiburon.

They found a house in Tiburon at a good price and we lent them $3M so they could buy straight away. The Carmel house goes on the market behind them.

Plans change, even after you have built the dream. You do not have to wait for the sale to act on it.

“I found the house. I still own mine.”

Moving Equity

How this works →
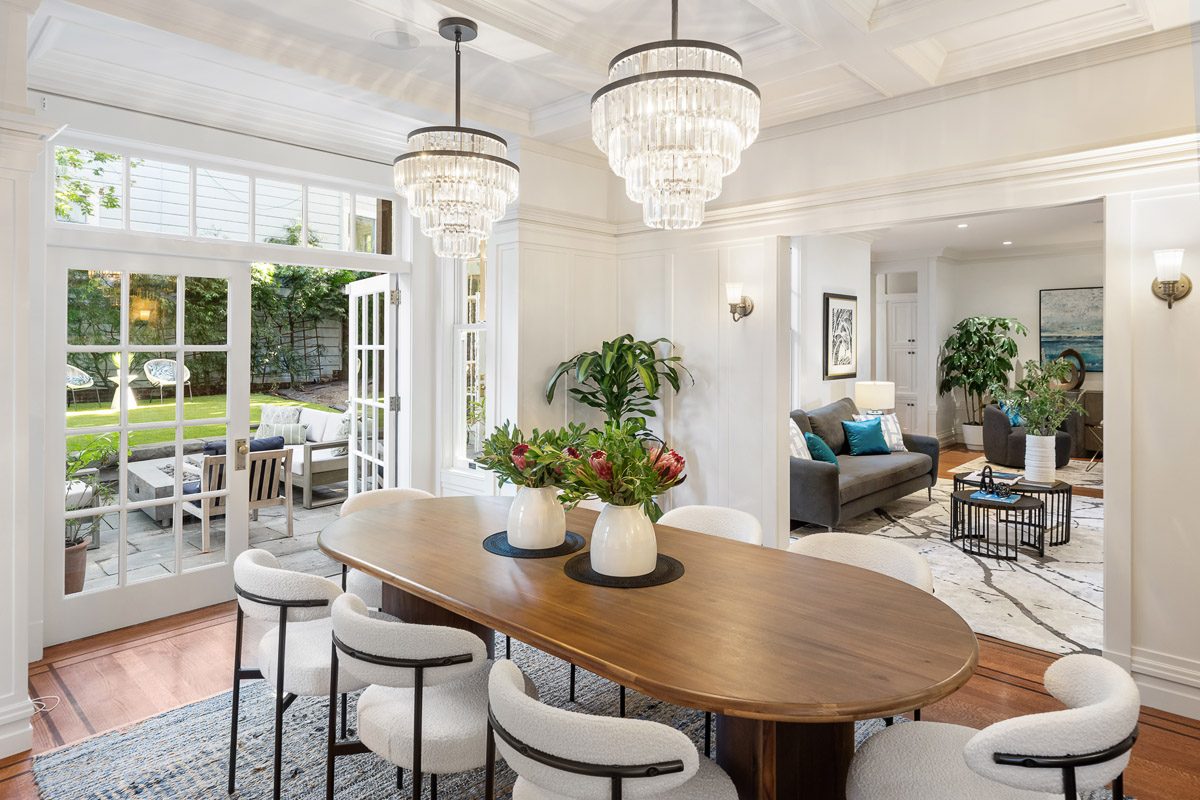
A dining room in a San Francisco home
Photo: Jennifer Rosdail Real Estate Team

Approved in twenty-four hours

Buying the next house without selling first

Our client was in a home worth around $5M with a small mortgage, and wanted to buy another at about the same price. Nothing competitive about it. He knew which house he wanted and had no intention of moving his family twice or selling first. Approved in twenty-four hours, offer made with no contingencies and no appraisal, closed in fourteen days.

Most of them are not dramatic. They are simply quick.

On the lagoon

A single level home, without selling the investments

Our client was in a three-storey house and wanted a single level where he could sit, watch the water and enjoy the rest of his life. He found one on the lagoon at a similar price, slightly higher. No stairs, room for the dogs, and space for his wife and his brother-in-law who is moving in. He gets around with a walker, and the house is ready for more than that if he ever needs it.

The financing was the interesting part. He had about $5.5M in a stock portfolio he did not want to liquidate. Working alongside his wealth advisor he borrowed a little against the portfolio, and the bridge loan covered the rest of the gap, so he never needed the full amount.

A portfolio loan and a bridge loan together can mean selling none of your investments.

“My deal is falling apart and we are close to closing.”

Saving the Deal

How this works →

Crossed with their condo

Ten days from closing, and the lender walked away

Our clients were ten days from closing when it started coming apart. Their bridge lender dropped the ball and said it could not be done, because the home had no certificate of occupancy yet. Their agent mentioned it to another agent, who told her to call us.

We looked, and it made sense. Our underwriter walked the property and we needed no appraisal. The bones were solid and the certificate was clearly coming. The clients were strong, bank-quality borrowers at a comfortable loan to value, and we crossed the loan with their condo. The only problem was the missing certificate, and we have room to work around something like that. We do not force square clients into round holes.

They were nervous and so was their agent. Neither believed we would pull it off. They rang several times a day and texted late into the evening asking if we were sure. Every time the answer was the same. We closed. They moved in, their agent sold the condo for top dollar, and everyone went out for sushi.

A quick yes or a quick no is what stops a deal dying late.

“I recently brought Sofia into a transaction after another lender was unable to perform, and she immediately stepped in, assessed the situation, and got the deal back on track.”

Miriam Wells  ·  Google review

“I inherited a house and I am not sure what to do with it.”

Inheritance and Wealth Transfer

How this works →

Pleasanton to Sausalito

An inherited house that was not ready to sell

When our client's parents died she inherited the family home, worth about $3M and owned free and clear, but needing a great deal of work. For a while nobody knew what to do with it, so it sat empty.

Then she found a condo in Sausalito she wanted to make her own. The problem was timing: the inherited house was not ready to sell and she could not buy without that equity. We used the equity in the inherited home to lend her about $1.8M, a couple of hundred thousand above the purchase price. The extra turned the condo into her home and paid for the work needed to get the family house ready to sell.

You do not have to sell a house that is not ready. Its equity can fund your next home and the work on both.

Manhattan Beach to Point Richmond

Buying with a parent's equity before the house sold

Our client spent years travelling down to Manhattan Beach to care for her mother, who was very ill. Her mother died and left her the family home, owned free and clear and held in trust with our client as sole beneficiary.

Her mother had been clear about what she wanted: sell the house, and use it to buy in the place her daughter had always wanted to live. She found the right home and went into contract. It was a multiple offer situation, and to compete she offered to cover the agent commissions. It worked.

We are lending against the inherited home so she can buy without waiting to sell. The extra covers those commissions and lets her put some work into the new place before she moves in.

Families often arrive not knowing what to do after a parent dies. A parent's equity can become the next chapter, exactly as they hoped.

“I buy, improve and sell property.”

Fix and Flip

How this works →
A renovated kitchen
Photo: Jennifer Rosdail Real Estate Team

Novato, San Rafael and Greenbrae

Buying the next project with no money down

Our clients came to this country from South America with almost nothing. They worked construction, and about twenty-five years ago they bought a property in Novato and fixed it up. That first one went well, and they kept going.

We have been behind seven or eight of their deals over the last five to ten years, and they now come to us two or three times a year. The model is simple: the equity in a property they own free and clear buys the next property with no money down. Some projects are large renovations, some are nearer $200K to $300K.

Earlier this year they bought in San Rafael. We crossed it with a property they own outright, funded the full purchase price, and added more for the renovation. Later they found one in Greenbrae that had fallen out of contract. This time we crossed nothing. We modified the loan they already had with us and moved the note around internally so they never had to pay it off, which freed up more money for the work on better terms.

Equity in one property buys the next with nothing down, and an existing loan can often be restructured rather than repaid.

Occidental

When the new property is almost impossible to insure

Our client owned an investment property in Occidental and was getting ready to sell it. He found another in Occidental at a lower price that needed work, and got a good deal because he came in with a bridge loan: no contingencies, no appraisal.

The interesting part was insurance. Occidental is hard to insure. So we placed the loan only on the property he already owned and pulled the equity out of that one. Because the new purchase was not part of the loan, he did not need to insure it. He kept the cover he already had, which mattered a great deal to him. No appraisal on either property. We were ready to close in five days and closed in ten, waiting on everybody else.

Where insurance is hard to get, the loan can sit entirely on the property you already own.

Tiburon and Belvedere

Financing the purchase and the build together

Our client is a well known builder in Tiburon and this is his eighth project there. He had watched a property in Belvedere for months and finally got it at a good price.

We crossed one of his Tiburon properties with the Belvedere purchase and wrote the loan in two parts: the full purchase price, plus a construction loan on top. He pays nothing on the construction portion until construction actually starts. He told us he could not find that much money for both the purchase and the project anywhere else. When it is finished it looks out over the water, the bay and the Golden Gate Bridge.

Purchase and construction in one structure, with nothing owed on the build until the build begins.

“I need capital fast, and it is not for a house.”

Hard Money and Founder Loans

How this works →

Tiburon

One loan for the renovation and the opportunity

Our client owns a home in Tiburon he plans to list in the spring. Before listing he wanted to renovate, and at the same time a business opportunity came up that he did not want to pass on.

We wrote a new first mortgage of $3M. It paid off the existing first, covered the renovation, and freed the capital for the opportunity.

One loan can clear the old mortgage, pay for the work, and fund something else entirely.

San Francisco and Sausalito

Payroll covered while the funding round closed

Our client owns a very successful San Francisco company. His next funding round was taking longer than expected and he needed $2M to make payroll and keep the business running.

He owned a property in Sausalito free and clear, so we lent $2M against it and he put it straight into the company. He planned to hold the loan sixty to ninety days and repay as soon as the round closed. Because we charge no prepayment penalty, he could pay us off the moment the capital arrived.

People ask why not a line of credit. Three reasons. Speed: he was fully approved within hours, there was no appraisal, our underwriter walked the property, and funds landed in three business days. Size: he could not have drawn a line that large. Purpose: home equity lines are meant for money that goes back into the property, not into a business.

Real estate you already own can cover a cash flow gap in days, and you are free to repay the moment your funding lands.

Bring us yours.

Four simple questions and one straight answer.

See your buying power
(415) 706-8465 See your buying power
Golden Gate Lending Group DRE #01405277  ·  NMLS #241012 Equal Housing Opportunity
Scotsman Guide Top Private Originators 2026 Better Business Bureau Accredited Business Equal Housing Opportunity
SituationsBuy Before You Sell RightsizingSave The Deal
LoansOwner-Occupied Bridge Fix and Flip / InvestmentFounder Capital BridgeHard Money Bridge
CompanyAboutReviews In the mediaLibraryFAQ
Talk to us(415) 706-8465 81 Casa Buena Dr, Suite 5, Corte Madera, CA 94925