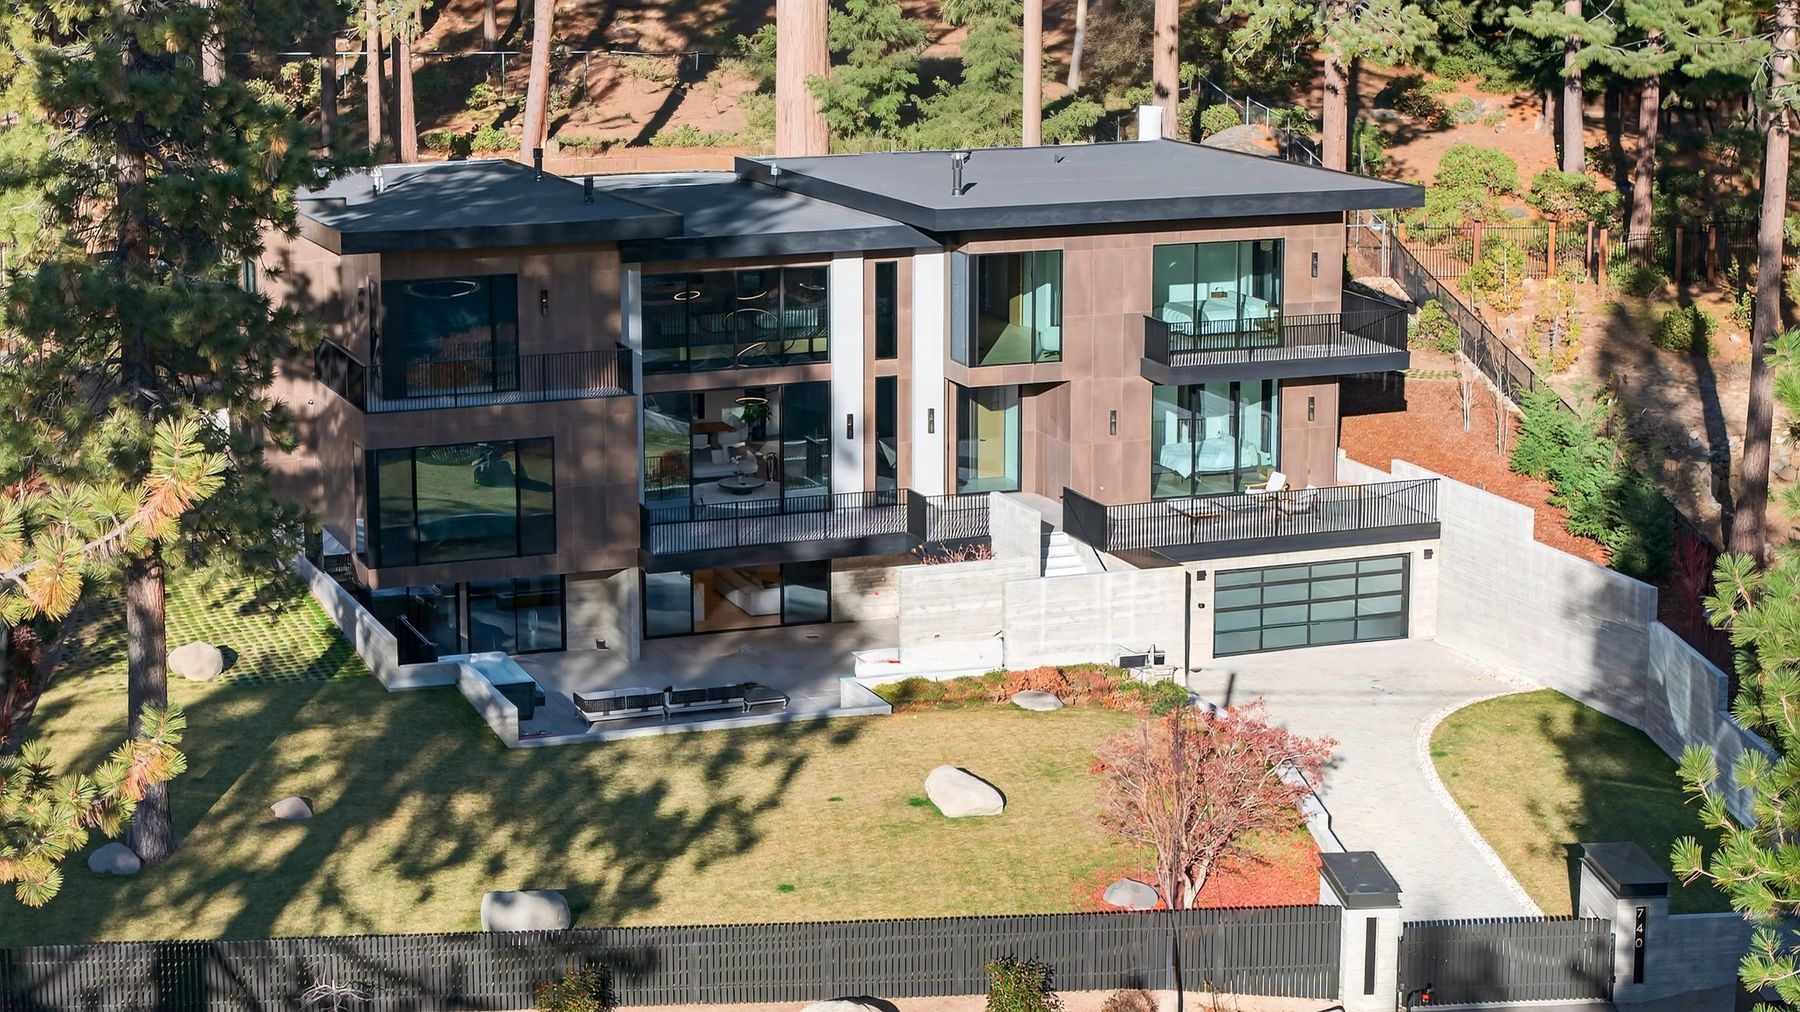
Photo: Milana Real Estate Group
Owner-Occupied Bridge Loans in California.
A bridge loan collateralized against the home you live in and the one you are buying, so you can purchase the next one before this one sells.
Photo: Milana Real Estate Group
A bridge loan collateralized against the home you live in and the one you are buying, so you can purchase the next one before this one sells.
In one line
A bridge loan secured by the home you live in and the home you are buying, so you can close on the new one before selling the one you are in.
Most private lenders cannot write owner-occupied loans at all, because they are held to consumer protection rules. That gap is the center of what we do.
Owner-occupied lending is held to consumer protection rules that investment-property lending is not. That extra compliance is why most private lenders will not touch it, and it is exactly the gap we were built for.
Practically, it means you can use the equity in the home you live in without selling it first, without a sale contingency weakening your offer, and without moving into a rental in between.
Rates and limits depend on the property and the file. Nothing here is a commitment to lend.
There is a great deal of cash in this market and strong buyers will not come forward with contingencies. You have to be able to compete with that. Sometimes it is simpler still: you find your dream home before you are ready to sell, and you have to move fast.
It also removes the second move. You go straight from the house you own into the one you bought, and your agent gets a vacant home to prepare, stage and sell properly.
The four programs
What separates them is not the price. It is what secures the loan and who is allowed to have it.
| Most lenders cannot write thisOwner-occupied bridgeOwner-occupied | Fix and Flip / InvestmentFix and Flip | Founder CapitalFounder | Hard Money BridgeHard Money | |
|---|---|---|---|---|
| Who it is for | Homeowners moving up, rightsizing or relocating within CaliforniaHomeowners | Real estate investors and realtors running their own projectsInvestors and realtors | Founders and business owners with a cash flow constraintFounders and owners | Investors and developers with a defined exitInvestors, developers |
| What secures it | The home you live in and the home you are buyingBoth homes | The property and the planThe property | A primary residence or an investment propertyA home you own | The real estate rather than your incomeThe real estate |
| Property type | The home you live inWhere you live | Single property or multiple projectsOne or several | California propertyCalifornia | Investment property onlyInvestment only |
| Prepayment | No penaltyNone | No penaltyNone | No penaltyNone | No penaltyNone |
| Worth knowing | Interest-only, repaid when the existing home sells. Typically 65 to 70 percent measured across both properties, less existing liens.65 to 70% of both homes, less liens | Always interest-only, with the term sized to the renovation and the exit.Interest-only, sized to the exit | $500,000 to $10M, funded in five to seven days, no appraisal and minimal paperwork.$500K to $10M, five to seven days | Always interest-only and short term by design.Interest-only, short by design |
Rates and limits depend on the property and the file. Nothing here is a commitment to lend.
Yes. It is a consumer loan and held to those rules, which is why it takes a licensed lender rather than a general private lender.
Typically 65 to 70 percent measured across both properties, less what you owe. The qualifier gives you a range in about ninety seconds.
Nothing. Use the qualifier or call, and you get a real answer either way, with the reason behind it.
That is the normal case. We measure across both properties and subtract what you still owe, so an existing mortgage reduces the figure rather than ruling you out.
Twelve months, interest only, repaid when your existing home sells. Most run sixty to ninety days.
 How to buy before you sell: a complete roadmap
 Can I buy a new home before selling my current one?
 Rightsizing in retirement: a financial planning guide
Property photography: The House
Four simple questions and one straight answer.
Golden Gate Lending Group Inc. · California DRE #01405277 · NMLS #241012 · Equal Housing Opportunity. Loans are made or arranged pursuant to a California Department of Real Estate license. This site is not a commitment to lend, and all loans are subject to underwriting and property approval.